Mighty Fin
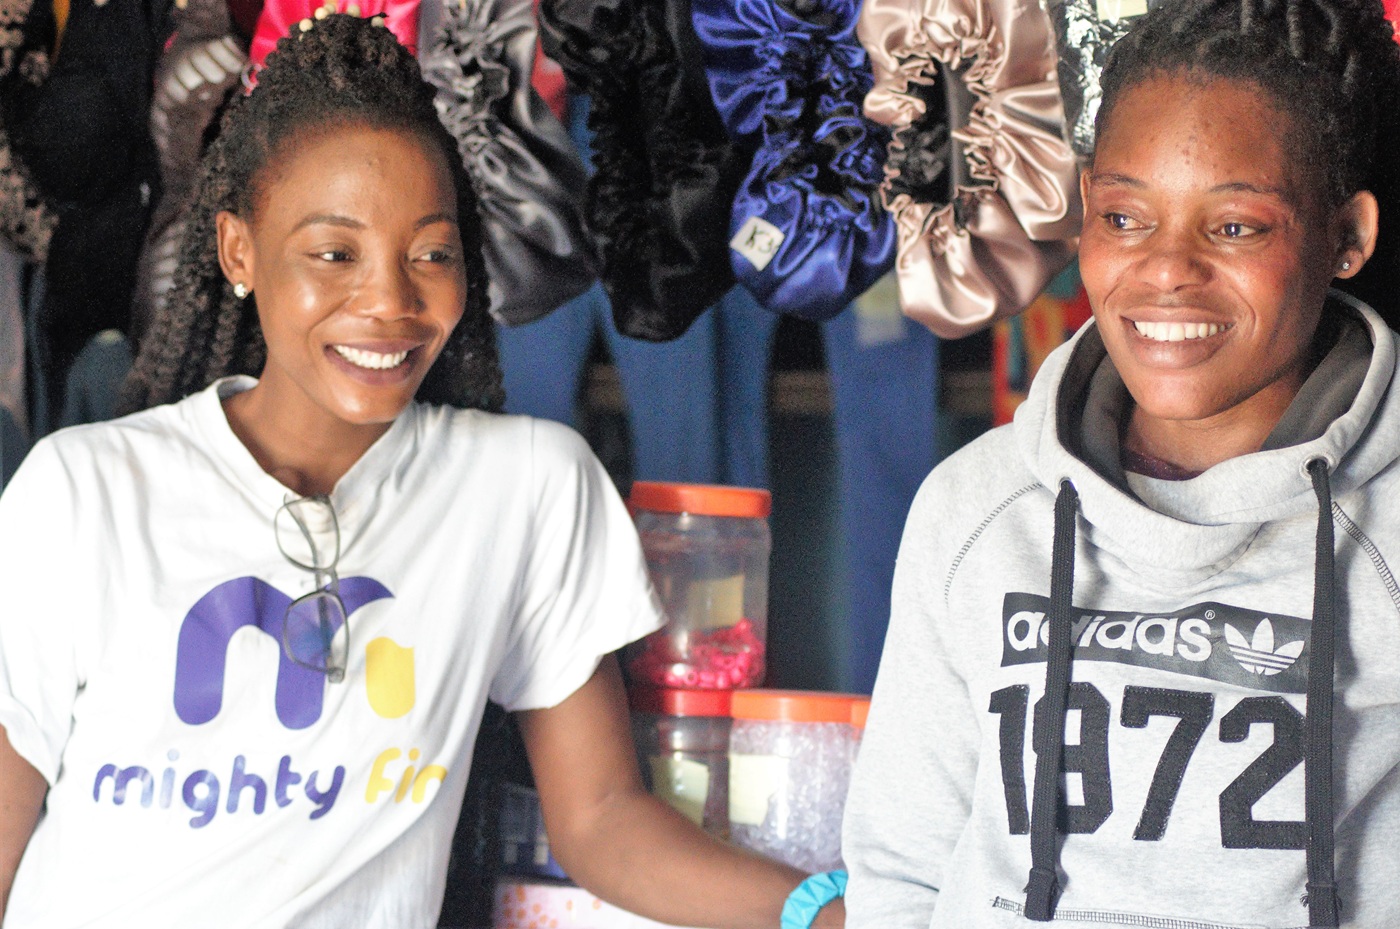
Mighty Finance Solution Limited (Mighty Fin) is closing the credit gap for Zambia’s micro, small, and medium enterprises. Through a digital lending platform and embedded finance partnerships, Mighty Fin delivers fast, collateral-free working capital to businesses that traditional banks cannot economically serve — using AI-driven cash flow analysis in place of collateral and credit history. Since 2022, Mighty Fin has disbursed 56,000 loans to 8,000 borrowers, with over 60% of them being women or women-led businesses.
The Problem
Micro, small, and medium enterprises (MSMEs) are the backbone of Zambia’s economy, employing 90% of the workforce and generating roughly 70% of GDP. Yet only 2.2% can access credit. Banks require collateral that often exceeds 100% of the loan amount, a requirement most MSMEs lack. In addition, 96% operate informally without financial records, and 94% have no bank account, making it difficult for lenders to assess creditworthiness. Even when borrowers overcome these barriers, manual underwriting and branch-based servicing make small loans too costly for banks to issue profitably. As a result, the businesses driving Zambia’s economy lack the working capital needed to buy stock, bridge receivables, and grow. Women entrepreneurs — who are disproportionately informal and unbanked — face even greater barriers. Closing this gap requires a lender built for how these businesses actually operate: digitally, without collateral, and based on real cash flows.
The Solution
Mighty Fin expands MSME access to credit through two complementary channels. The first is a direct digital lending platform where borrowers apply online and receive a credit decision within hours, not weeks. The second is embedded finance: working capital delivered through intermediary partners within the ecosystems where MSMEs already operate, including agriculture and fast-moving consumer goods value chains. By embedding credit at the point of need, Mighty Fin finances real, verifiable economic activity while reaching businesses traditional branch networks cannot serve economically.
Three integrated layers power Mighty Fin’s model: 1) Cash flow intelligence: An AI-powered underwriting engine uses real-time transaction data to assess creditworthiness, replacing collateral and credit histories. 2) Embedded distribution: Financing is delivered through partner platforms and value chains, reducing costs and reaching businesses where they already operate. 3) Revenue-linked repayment: Repayments are automatically deducted from business revenues, aligning payments with cash flow and reducing repayment risk. Together, these layers enable Mighty Fin to profitably serve underserved MSMEs that traditional lenders cannot.
By 2031, Mighty Fin plans to deepen partnerships in agriculture and fast-moving consumer goods (FMCG), add new value-chain partners that provide access to established MSME networks, and expand into Botswana and Malawi. Mighty Fin’s long-term vision is a pan-regional embedded finance platform that enables value-chain partners to provide affordable working capital to millions of underserved MSMEs.
Impact
8,000 MSME borrowers served across 56,000 loans disbursed since 2022, with over 60% of them being women or women-led businesses.
Financing real economic activity across Zambia through direct lending and embedded partnerships in key value chains.
96% collection rate and 72% repeat borrowing demonstrate affordable, well-matched credit that drives business growth.
Leadership
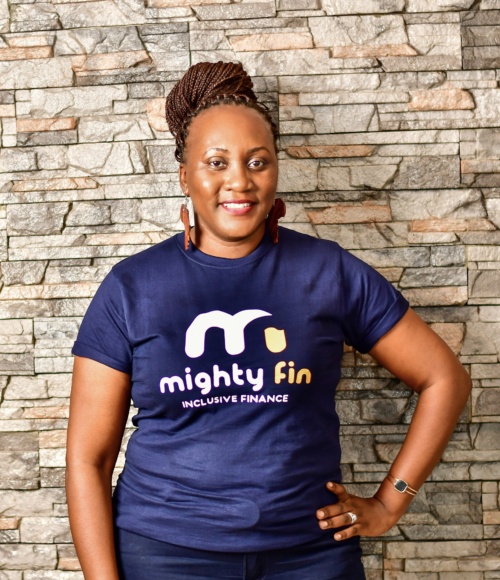
Vwanganji Bowa
Vwanganji, founder and CEO, is a Zambian socio-development economist with 15 years of experience in financial inclusion, economic development, entrepreneurship, and stakeholder engagement. She holds an MA from the University of Zambia, and is pursuing a Ph.D. focused on women’s economic empowerment through digital finance, informing Mighty Fin’s gender-lens lending model and 60% women-led borrower base. She is a Fortune US Department of State Global Women’s Mentoring Partnership alumna.